Last updated: 22 October 2026 · Written by Axel
S455 tax is a Corporation Tax charge your company pays when you, as a director who also owns shares, owe the company money at the end of its accounting period and have not paid it back within 9 months. For loans made on or after 6 April 2026 the rate is 35.75% of the amount still outstanding (33.75% for loans made from 6 April 2022 to 5 April 2026). The important bit most people miss: it is a timing cost, not a fine. Clear the loan in time and there is nothing to pay. Clear it late and you pay, then claim it back.
What counts as a director's loan
GOV.UK defines a director's loan as money you, or close family, take from the company that is not a salary, a dividend, an expense repayment, or money you put in earlier. In real life it usually looks like this:
- The company paid the deposit on a van that is in your name, not the company's.
- You moved £3,000 across to cover the mortgage in a slow month.
- You bought your own tools or a family holiday on the company card.
- You took "drawings" like a sole trader, with no payroll or dividend paperwork behind them.
Every one of those goes on the director's loan account, the running record of what you owe the company and what it owes you. If you owe it, the account is overdrawn. That record also goes on the balance sheet in your annual accounts, so it is not something you can tidy up quietly later.
My honest view: if you used to be a sole trader, this is the single biggest habit to break. In a limited company the money in the bank is not yours until it comes out as salary, dividend or a repaid expense.
The s455 rate and the deadline
The HMRC manual at CTM61505 sets out the rate history. The s455 rate is tied to the dividend upper rate, so it moved up when dividend tax rose in April 2026.
| Loan made | S455 rate |
|---|---|
| Before 6 April 2016 | 25% |
| 6 April 2016 to 5 April 2022 | 32.5% |
| 6 April 2022 to 5 April 2026 | 33.75% |
| On or after 6 April 2026 | 35.75% |
The clock runs from your company's year end:
- Year end. Whatever you owe the company on this date is the figure that matters.
- Within 9 months. Repay the loan in this window and no s455 is due. You still show it on the return.
- 9 months and 1 day. This is when Corporation Tax is due for companies with taxable profits up to £1.5 million, and when any s455 on the unpaid balance is payable too. Pay late and HMRC adds interest.
How it shows on the CT600 and CT600A
S455 does not live on the main CT600 boxes alone. You complete the CT600A supplementary page (loans to participators by close companies) whenever a loan to a director-shareholder was outstanding at the year end, even if you repaid it within the 9 months. CT600A is where you show the loan, any repayments made after the year end and before the return, and the s455 that results. The figure then flows into the total tax on the CT600.
A loan made and repaid in the same accounting period, with nothing outstanding at the year end, does not need to go on the return. If the loan is part of a pattern of repaying and re-borrowing, it does.
If you are filing yourself, our step by step on how to file a CT600 yourself covers where the supplementary pages fit.
A worked example with real numbers
Dan is a roofer with his own limited company. His year end is 30 September. In May 2026 the company pays £18,000 towards a pickup that is registered to Dan personally. Nothing else goes through his loan account, so at 30 September 2026 he owes the company £18,000.
- S455 at stake: £18,000 x 35.75% = £6,435.
- Repay by 30 June 2027 (within 9 months of the year end) and the s455 is nil. He still completes CT600A.
- Repay nothing, and the company pays £6,435 with its Corporation Tax on 1 July 2027.
- Repay in December 2027, and the company can reclaim the £6,435, but only from 9 months and 1 day after the end of the accounting period in which he repaid: 1 July 2029 if the next year end is 30 September 2028. Any interest charged on the s455 is not refundable.
That is the real cost of a late repayment: about two years of your company's cash sitting with HMRC. That is why I call it a timing cost. It is still a nasty one for a small company.
There is a second issue. Dan owed more than £10,000 during the tax year, so the loan is no longer exempt as a beneficial loan. The company reports a benefit in kind on a P11D and pays Class 1A National Insurance on it, and Dan pays income tax on the benefit. The benefit is worked out using HMRC's official rate of interest, which is 3.75% for 2026 to 2027, less any interest Dan actually pays. Charge yourself interest at the official rate and the benefit goes away.
Ways to clear the loan
| Method | How it works | Watch out for |
|---|---|---|
| Cash | You pay the money back from personal funds | It must be a real, permanent repayment |
| Dividend | Company declares a dividend credited to your loan account | Needs enough retained profit, and you pay dividend tax |
| Salary or bonus | Bonus run through payroll and credited to the account | PAYE and National Insurance on top |
| Write-off | Company releases the debt | Class 1 National Insurance through payroll and income tax via Self Assessment |
From 6 April 2026 dividend tax is 10.75% at the ordinary rate, 35.75% at the upper rate and 39.35% at the additional rate. Clearing a large loan with a dividend can push you into the higher band, so run the numbers before you vote yourself one.
The bed and breakfasting trap
"Bed and breakfasting" means repaying the loan just before the deadline and borrowing it straight back. HMRC closed this years ago with two rules:
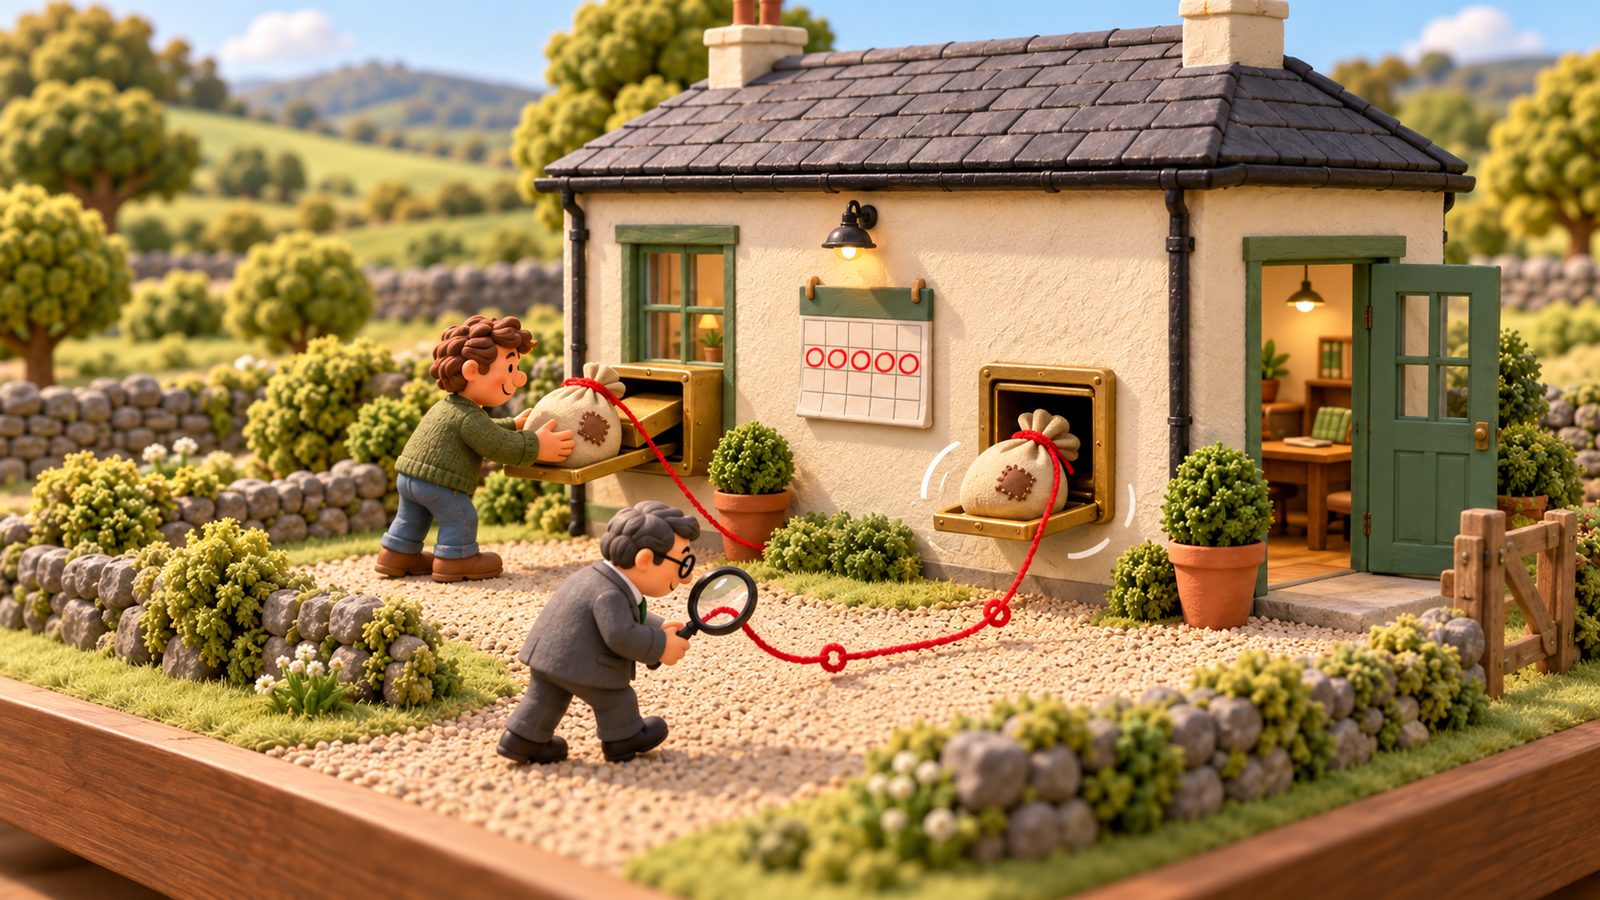
- The 30-day rule. If you repay £5,000 or more and, within 30 days of that repayment, the company lends you £5,000 or more in a later accounting period, the repayment is matched to the new loan, not the old one. The original loan stays outstanding and s455 applies.
- The arrangements rule. If you owe at least £15,000 and, when you repay, you have already arranged to borrow £5,000 or more again, the same matching applies. There is no time limit on this one.
The exception: a repayment that is itself taxed on you, such as a dividend or a PAYE bonus credited straight to the loan account, is outside these rules. Taking the dividend out in cash and paying it back in does not count.
What to do if your loan account is overdrawn
- Get the real balance. Go through the bank statements and list every personal payment. Guesswork here is how people get caught.
- Note your two dates. The 9 month repayment window and the 9 months and 1 day payment date. Our Companies House deadlines guide and the CT600 filing deadlines page help you pin both down.
- Pick how you will clear it. Cash if you have it, a dividend if there is retained profit, or accept the s455 for now and plan the reclaim.
- Charge interest or report the benefit if you were over £10,000 at any point in the tax year.
- Complete CT600A with the return, and file on time. Late filing brings its own penalties from Companies House and HMRC.
Be honest with yourself about when this needs an accountant. If there are several shareholders, loans to relatives, a pattern of repaying and re-borrowing near the deadline, loans being written off, or a balance big enough that the bed and breakfasting rules could bite, pay for proper advice. The rules are mechanical, but the anti-avoidance side is not something to learn on your own company.
Quick answers
Frequently Asked Questions
01Is s455 tax a penalty?
No. It is a temporary Corporation Tax charge that you can reclaim once the loan is repaid, released or written off. The parts you lose are the interest on late-paid s455 and the cash tied up until the refund date.
02What is the s455 rate in 2026?
It is 35.75% for loans made on or after 6 April 2026 and 33.75% for loans made between 6 April 2022 and 5 April 2026. The rate follows the dividend upper rate.
03Do I pay s455 if I repay the loan before the deadline?
No. If you repay within 9 months of the end of the accounting period, no s455 is due. You still show the loan on form CT600A.
04How do I reclaim s455?
Claim on CT600A for the period the loan was taken out if you are within 2 years of that period's end, or use form L2P otherwise. HMRC will not repay before 9 months and 1 day after the end of the period in which you repaid, and you must claim within 4 years of the end of the financial year in which the loan was repaid, released or written off.
05Does an overdrawn loan under £10,000 still need reporting?
Yes, if it is outstanding at the year end it goes on CT600A and on the balance sheet. The £10,000 limit only decides whether there is also a benefit in kind to report on a P11D.
Once the loan is sorted and the numbers are right, the filing itself is the easy bit. A.X.E.L Filing lets you file your micro-entity accounts and CT600 straight to Companies House and HMRC with your own Government Gateway login, for £49 for both. Start your return here.
A.X.E.L Filing
Accounts and CT600, filed in one sitting.
Prepare your accounts and Corporation Tax return with the tax worked out as you type, next to your own Self Assessment, and let your AI run the what-ifs. Then file to Companies House and HMRC yourself. No accountant fees, no subscription.
£20 for a dormant company
Records in a mess? See what you need, and let your AI do the sorting →